

Summary:
The 50/30/20 rule is a straightforward budgeting framework that allocates 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt repayment, promoting balanced financial management.
Challenges such as inconsistent income, high living costs, or a heavy debt load might require adjustments to the standard 50/30/20 allocations to better fit individual financial situations.
Flexibility in the budget allows for adjustments based on personal financial changes, and regular budget reviews help adapt the plan to ensure it continues to meet financial goals effectively.
CreditAssociates® can assist you in managing your budget and overcoming debt with professional advice tailored to your financial needs, schedule a free consultation today to learn how we can help you secure a financially stable future.
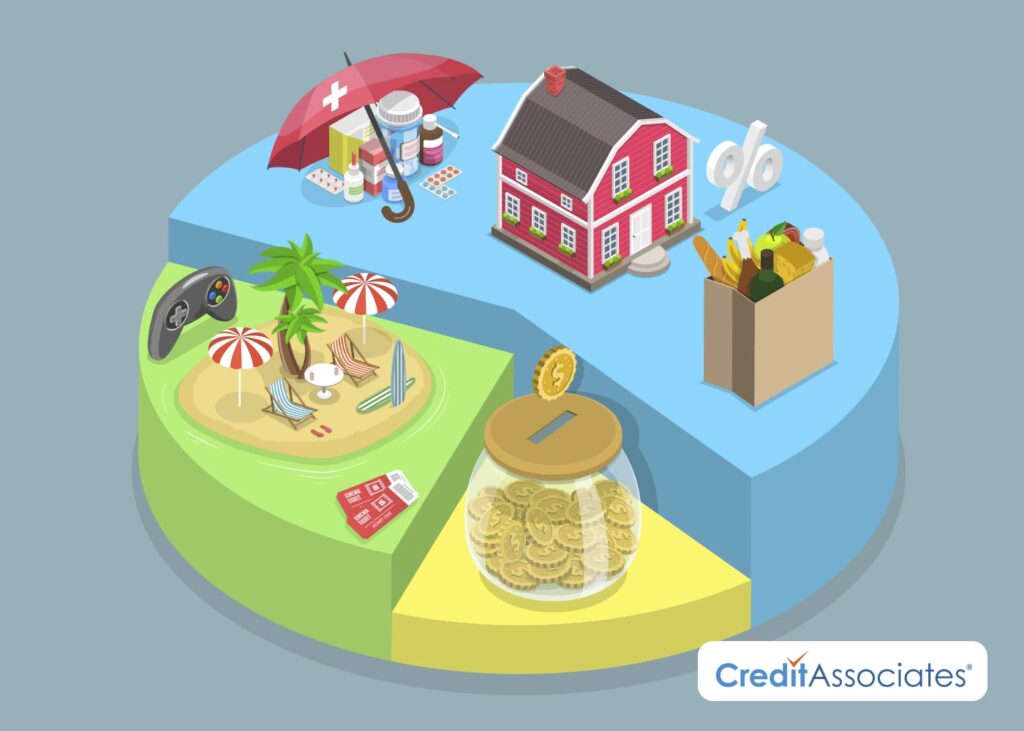
Budgeting doesn’t have to be complicated. Imagine a straightforward method where you just split your income into three big parts: one for the essentials, one for the fun stuff, and one for your future. This is what the 50/30/20 rule is all about. It’s a budgeting approach that’s simple but remarkably effective, helping you manage your finances by allocating 50% of your income to needs, 30% to wants, and 20% to savings and debt repayment. Needs are the must-haves like rent and groceries, wants include leisure and non-essentials, and savings … well, that’s for your future self!
The Practicality and Flexibility in Implementing the Rule
Implementing the 50/30/20 rule requires meticulous organization and commitment to mindful spending and saving. Here’s how you can break down the process into actionable steps.
Calculating After-Tax Income
Begin by determining your after-tax income. This is the amount you have left after all deductions, such as taxes and social security, have been subtracted from your total earnings. It’s crucial to base your budget on this figure to ensure accuracy in allocation.
Developing Spending Categories
Once you have a clear understanding of your net income, identify and establish your spending categories: needs, wants, and savings or debt repayment. Each category serves a specific purpose in your overall financial management.
Allocating to Needs
Allocate 50% of your after-tax income to your needs. This includes essential expenses such as rent or mortgage, utilities, groceries, and any other non-negotiable payments that you need to make each month.
Assigning to Wants
Designate 30% of your budget towards your wants. This might encompass non-essential spending like dining out, entertainment, shopping, or investing in hobbies, such as a gym membership or other recreational activities.
Directing Towards Savings or Debt Repayment
Lastly, direct the remaining 20% of your income towards savings or debt repayment. This portion is vital in building your financial stability, ensuring you’re preparing for the future, and clearing any existing financial liabilities.
By adhering to these steps, the 50/30/20 rule can act as a robust framework, facilitating structured spending and promoting healthy financial habits. This, in turn, ensures a balanced approach to managing your money, fostering a financial environment that supports your current lifestyle while safeguarding your future.
Potential Challenges and Smart Adjustments
- Rigid Categories: Some might find the distinction between needs, wants, and savings too rigid or unsuitable for your financial situation.
- Inconsistent Income: For freelancers or gig workers, variable incomes can pose a challenge in maintaining a consistent budget.
- High Cost of Living: In certain cities or regions, allocating only 50% for necessities might be impractical.
- Heavy Debt Load: For you with substantial debt, more than 20% toward savings and debt repayment might be required.
- Overspending on Wants: It may be tempting to overspend in the “wants” category, potentially derailing the budget.
The 50/30/20 rule, while a great starting point, may need adjustments to cater to your personal needs and lifestyle effectively. One key to navigating these challenges is flexibility and customization. For inconsistent incomes, planning around the lowest expected monthly earnings and allocating any extra towards savings or unexpected expenses can be a prudent strategy. Suppose you’re in an area with a high cost of living. In that case, tweaking the percentages to ensure all necessities are covered, even if it means adjusting your savings or wants categories, is vital.
Regular reviews of your budget, adjusting for any misclassifications or changes in financial goals and circumstances, and utilizing tools like budgeting apps or spending diaries can aid in keeping spending in check and ensuring that your budget evolves along with your financial journey.
The Bigger Picture – Financial Wellness and Future Planning
The 50/30/20 rule is more than just a technique for handling your monthly finances; it acts as a gateway toward achieving overarching financial wellness and securing a stable financial future. When you allocate that crucial 20% toward savings, you’re not just crafting a safety net to fall back on during tough times. This strategy is also about meticulous future planning and constructing a foundation for accumulating wealth as time progresses. You can utilize that saved money for various future goals, such as a serene retirement, strategic investments, or even acquiring your dream home.
The rule nurtures a disciplined spending behavior while promoting an active saving mindset. This ensures that you’re not only adeptly managing your present financial obligations but are also steadfastly paving the way toward a secure financial future. The 50/30/20 rule, therefore, furnishes you with a lens through which you can visualize and structure your financial journey, ensuring a balanced, disciplined, and future-oriented approach to managing your monetary resources effectively.
Finding Your Perfect Budgeting Approach
While the 50/30/20 rule offers a fantastic framework, it’s also beneficial to explore and understand alternative budgeting methods. Personal finance is just that — personal. Your friend’s preferred budgeting strategy might not quite fit your financial footprint. Exploring varied methods, from zero-based budgeting to the cash envelope system, allows you to discover what genuinely works for you. The goal is to find a method that not only helps you manage your money but does so in a way that aligns with your lifestyle, goals, and financial aspirations.
CreditAssociates® is Here to Help
Are you ready to take control of your finances and build a brighter financial future? Our dedicated team of financial experts is here to help guide and support you every step of the way. Visit our website today to get started on your financial journey!
Common Questions
How do I determine my after-tax income?
Your after-tax income is the total income you have left after all deductions, like taxes and retirement contributions, have been made. It’s essentially the money you take home.
What if my living costs exceed 50% of my income?
High living costs may require adjusting the percentages to make the rule workable for your situation. You might tweak the allocation to ensure all essential expenses are covered while maintaining a savings strategy.
What should I do if I consistently need help to stick to the rule?
Reevaluate your allocations, explore additional ways to increase income or decrease expenses, and consider seeking advice from a financial advisor.